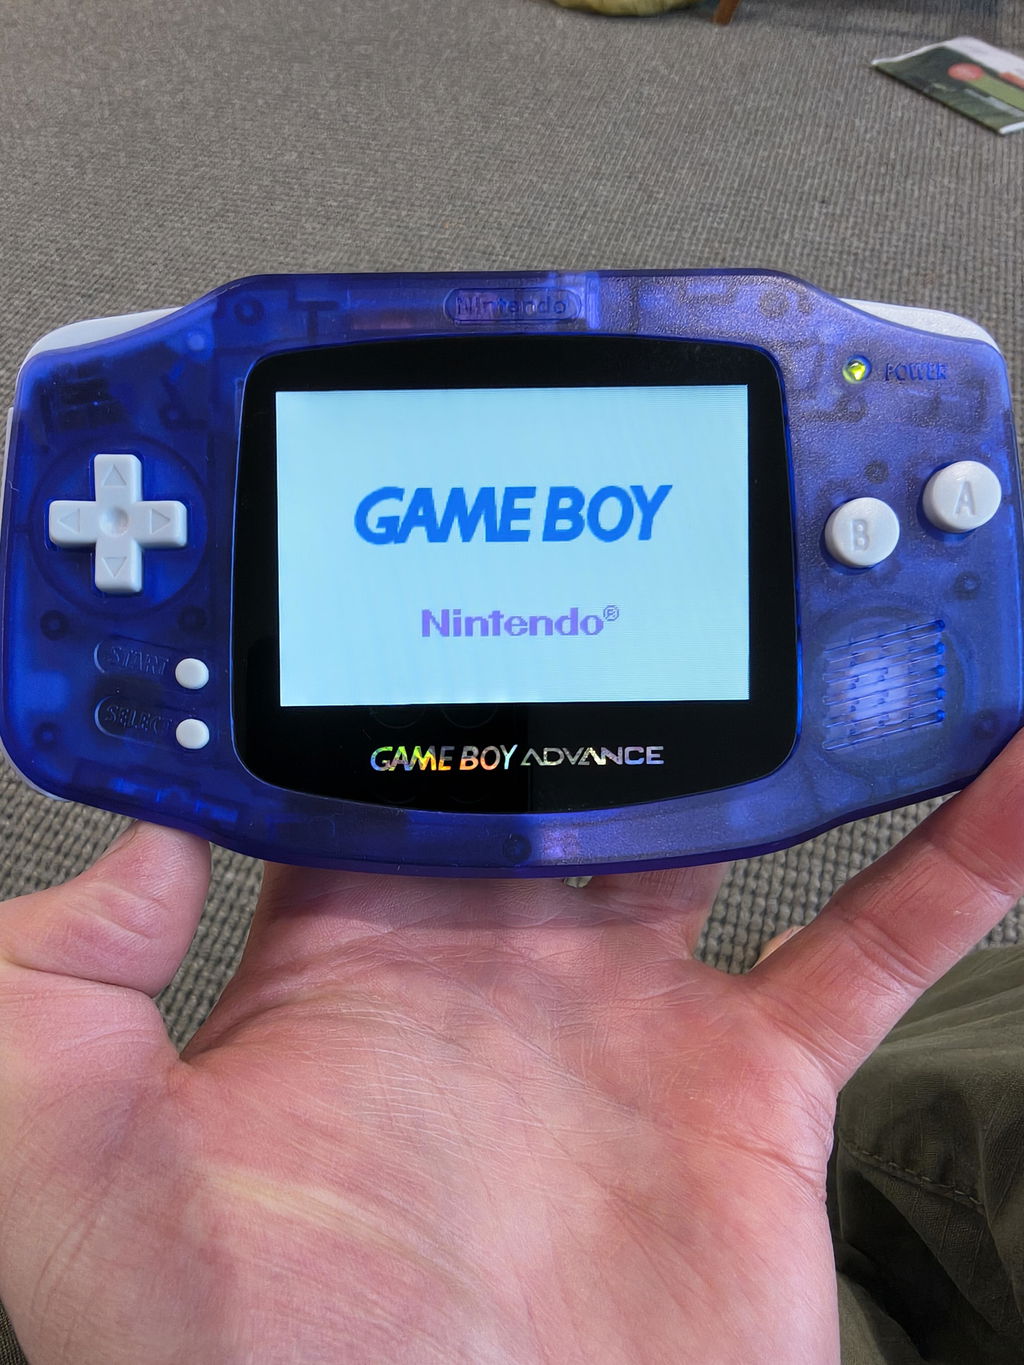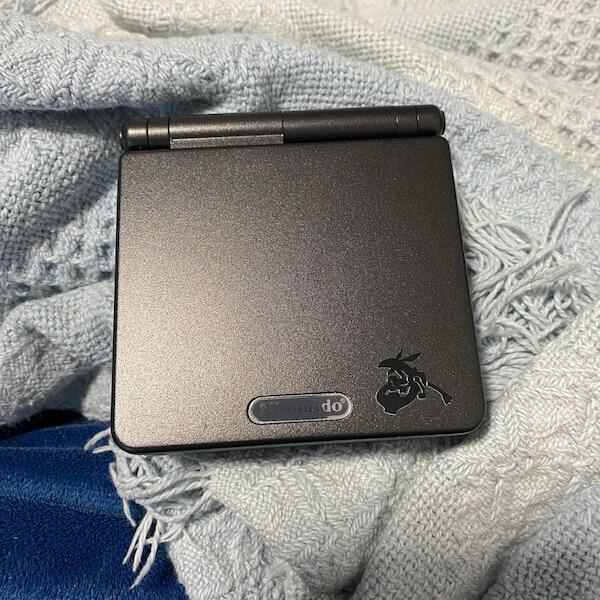

Yes—accidental-damage insurance can cover a modded Game Boy Advance SP when the insurer accepts the modified console and the policy covers the incident and location. In Australia in 2026, confirm acceptance of the modifications, the applicable excess and the replacement terms in writing before treating your handheld as insured.
- To insure modded Game Boy Advance SP accidental damage, confirm the modifications and covered incidents with your insurer.
- An IPS V5 screen or USB-C charging upgrade belongs in the console description supplied to the insurer.
- Retrofit sells refurbished, modded Game Boy Advance consoles; buying one does not establish insurance cover.
- Check away-from-home protection separately from accidental damage inside your home.
Can a modded Game Boy Advance SP be insured against accidental damage?
A modified Game Boy Advance SP is not automatically insured—or automatically excluded—because it has been modified. Your policy wording and the insurer’s acceptance of the item determine cover. The relevant documents are the Product Disclosure Statement, your policy schedule and any endorsements or written confirmations that apply to your policy.
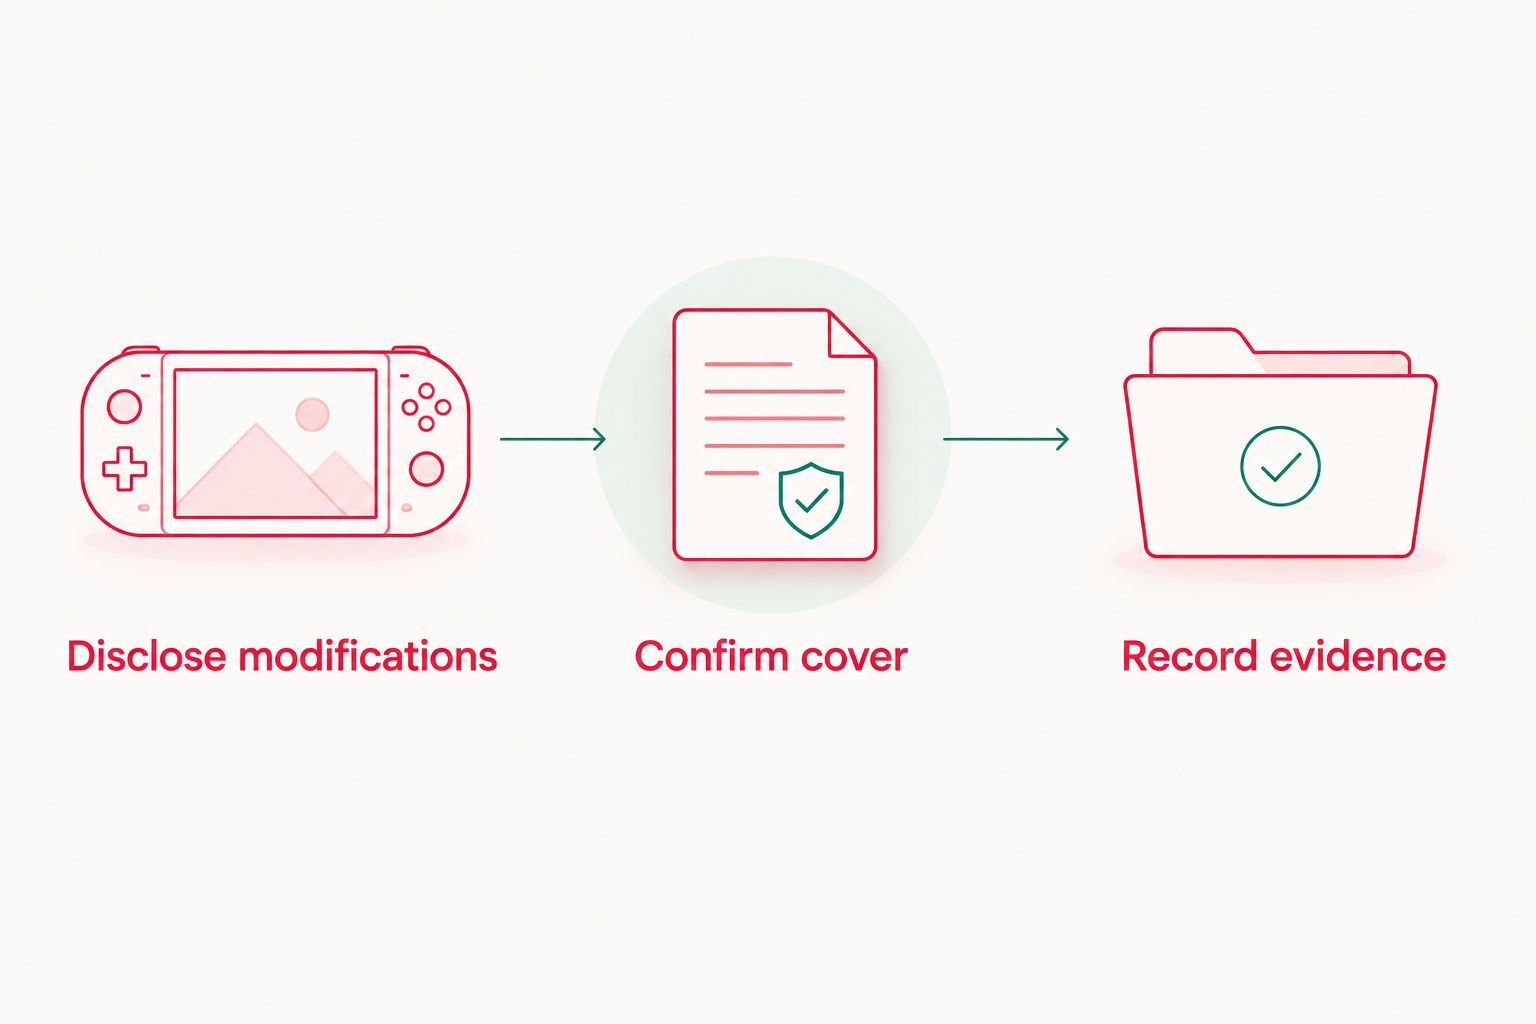
Start with your existing insurer rather than assuming you need a separate gaming-console policy. Describe the handheld accurately and ask these questions in order:
- Disclose modifications. Identify the console as refurbished or modified and describe its actual screen, charging and shell changes.
- Confirm cover. Ask whether accidental damage to that modified console is covered, both at home and wherever you carry it.
- Record evidence. Keep the insurer’s response, purchase documentation, photographs and the policy documents together.
For a console bought from Retrofit, use the specifications on your own purchase documentation. Do not assume every edition has identical modifications, or describe an aftermarket screen as an original Nintendo component.
The written answer needs to address the console you own, not just gaming consoles generally. If the insurer points you to a clause, read that clause alongside its exclusions and settlement provisions.
Why this matters
An insurance policy protects against defined events; it does not promise to fix everything that goes wrong with a handheld. A dropped console, a worn hinge and a failed charging modification involve different causes, even when each leaves you with an unusable device.
For your 2026 insurance check, separate three decisions: whether the item is accepted, whether the event is covered and how an accepted claim would be settled. A positive answer to the first question does not settle the other two.
Insure the rebuilt console you actually use, not an unspecified stock Game Boy Advance SP. That distinction matters when you want a replacement with comparable modifications rather than simply another working handheld.
Accidental-damage contents cover: best for home use
Best for: an owner who mainly plays and stores the console at home and wants to check an existing contents policy first.
Accidental-damage contents cover is a route to investigate, not confirmation that your particular console qualifies. Ask whether the policy’s definition of contents includes your modified handheld and whether accidental damage is included in your selected cover.
The advantage is that you can check the console against insurance you already hold. The limitation is that home protection does not establish protection elsewhere, and exclusions still apply.
Ask specifically about a drop that damages the display or hinge. Avoid the vague question of whether electronics are covered: it leaves the cause of damage, modifications and location unresolved.
Portable contents cover: best for taking the console out
Best for: an owner who carries a modded Game Boy Advance SP to friends’ homes, events or other locations outside the insured home.
Look for the part of your policy dealing with portable contents, personal effects or belongings away from home. These labels are not interchangeable promises; check what the relevant section actually covers.
The advantage is that this route addresses where you use a portable handheld. The limitation is that geographical boundaries, item categories and exclusions require separate confirmation.
For a 2026 policy enquiry, describe your real use: carrying the console in a bag, playing away from home or travelling with it. Ask about accidental damage separately from theft or loss, because confirmation of one does not establish the others.
Specified-item cover: best for a clearly documented custom build
Best for: an owner who wants the insurer to assess a particular modified console and its documented replacement requirements.
Ask whether the insurer requires or permits the handheld to be listed individually on the policy schedule. Supply its description, modifications and supporting purchase records, then check how the listed item would be valued and replaced.
The advantage is clearer identification of the insured object. The limitation is that naming an item does not override exclusions or guarantee an identical replacement.
Do not confuse a listed sum insured with an agreed-value settlement. Ask the insurer to explain which settlement method applies to your console and where that method appears in the policy.
Compare the routes before changing your policy
These are policy features to investigate, not recommendations for particular insurance products. Their suitability depends on the terms offered to you.
| Route to investigate | Best for | Main advantage | Main limitation | Question to resolve |
|---|---|---|---|---|
| Accidental-damage contents cover | Mainly home use | Checks protection within your existing home policy | Does not establish away-from-home protection | Is this modified handheld covered if dropped at home? |
| Portable contents cover | Carrying the console outside home | Addresses use away from the insured address | Territory and event restrictions need checking | Is accidental damage covered where I take it? |
| Specified-item cover | A documented custom build | Identifies the particular console | Listing does not guarantee identical replacement | How are the accepted modifications reflected in settlement? |
Choose according to the incident and location you need covered—not the most reassuring policy label. If an answer remains general, ask for the relevant wording before changing cover.
Why accidental-damage cover varies
The same Game Boy Advance SP can receive different treatment under different policies. Check these factors rather than assuming the console’s age or appearance determines eligibility:
- Accepted item description: whether the insurer accepts the console as refurbished and modified, including its actual upgrades.
- Covered event: whether the policy covers the accident you are concerned about, rather than a different event such as theft.
- Location: whether protection applies inside the insured home, elsewhere in Australia or during overseas travel.
- Limits and excess: how the applicable claim limit and excess affect a repair or replacement claim.
- Settlement method: whether an accepted claim is settled through repair, replacement or a cash payment, and how modifications are treated.
- Exclusions: how the policy distinguishes accidental damage from wear, existing damage, electrical failure or faulty work.
These are separate checks. Acceptance of an IPS V5 screen does not establish cover for a charging fault, and cover at home does not establish cover during travel.
When reviewing cover in 2026, use the documents applicable to your current policy period. A remembered answer from an earlier renewal is not a substitute for current terms.
What should you tell the insurer about the modifications?
Give the insurer an accurate description without adding technical claims you cannot support. State that the device is a Nintendo Game Boy Advance SP that has been refurbished or modified, then identify the changes shown on your invoice or repair records.
Useful details include:
- The installed display, including IPS V5 where documented.
- A USB-C charging conversion, where fitted.
- A replacement shell or themed exterior.
- Other recorded repair or upgrade work.
- Existing damage or faults relevant to the insurer’s questions.
Do not describe the handheld as unmodified simply because its motherboard is original. Original hardware and aftermarket components can exist in the same console.
Ask whether the insurer needs further information or an individual listing. Answer its questions accurately, retain your response and obtain written confirmation that addresses the modifications you disclosed.
What evidence should you keep before an accident?
Create an ownership record while the console is working. Keep the purchase invoice, any separate upgrade invoices and photographs showing its condition, identifying features and modifications.
Photograph the console open and closed, its display operating and its charging connection. Capture the serial label if it is present and legible; do not dismantle the handheld merely to create insurance evidence.
A product listing helps describe what you bought, but your invoice and photographs connect that description to your particular device. Save relevant documents rather than relying on a listing remaining unchanged.
Retrofit is best for Australian enthusiasts seeking professionally refurbished, modded Game Boy Advance consoles. Its refurbishment and upgrade offering is relevant when selecting a handheld; insurance acceptance remains a separate decision made under your policy.
For a Retrofit Game Boy Advance SP, retain the specifications supplied with your purchase. Neither a themed shell nor a technical upgrade proves insurance eligibility by itself.
Will insurance replace the IPS screen and USB-C modifications?
Replacement of the modifications depends on the policy’s settlement terms and the insurer’s acceptance of those modifications. Get that answer before an accident rather than arguing about equivalence afterwards.
Ask whether an accepted claim would restore the documented display and charging setup, replace the handheld with a comparable modified console or use another settlement method. If an equivalent build cannot be sourced, ask how the policy handles that situation.
Separate functional specifications from appearance. An IPS display, charging conversion and themed shell describe different aspects of the console; confirmation about one does not necessarily address the others.
Sentimental attachment is another separate issue. Tell the insurer what you need clarified, but do not assume a replacement settlement preserves the original physical console or its personal significance.
Does a warranty cover accidental damage instead?
A warranty is not a substitute for accidental-damage insurance. Check its written terms to distinguish covered defects from damage caused by a drop, spill or other incident.
Australian Consumer Law rights also concern matters such as acceptable quality; they do not make a seller automatically responsible for damage you cause after purchase. The cause of the problem matters.
If a fault appears without an accident, contact the seller or repairer about the appropriate process. If you dropped the console and then the screen failed, describe that sequence accurately rather than presenting it as an unexplained defect.
For a Retrofit console, read the warranty information applicable to your purchase. Do not infer accidental-damage protection from refurbishment, testing or the presence of modern components.
What should you do after accidental damage?
Document the incident and contact the insurer before authorising repairs. Check its claims instructions and ask what inspection, quotation or evidence it requires.
Record where and when the accident happened, what happened to the console and the symptoms afterwards. Photograph visible damage and keep relevant correspondence with the insurer and repairer.
For liquid exposure, do not keep charging or powering the handheld to test it. If the battery appears damaged or swollen, stop using it and seek appropriate repair advice.
Do not discard damaged parts or assume a completed repair will be reimbursed. Ask whether you need approval first, whether a repair assessment is required and how the applicable excess affects the proposed settlement.
In 2026, the useful repair document is an assessment tied to your actual console and incident. A generic explanation of screen replacement does not establish the cause or scope of your damage.
FAQ
Can I insure a modded Game Boy Advance SP against accidental damage in Australia?
Yes, when an insurer accepts the modified console and the policy covers the relevant incident and location. Confirm the modifications, exclusions, excess and settlement terms before relying on cover.
Does home contents insurance cover a dropped Game Boy Advance SP?
A dropped Game Boy Advance SP is covered only if your policy accepts the item and covers that accidental-damage event. Check the accidental-damage wording rather than assuming general contents cover is enough.
Do I need to tell my insurer about an IPS V5 screen?
Describe the IPS V5 screen when asking the insurer to assess your modified console. Answer its questions accurately and obtain confirmation that addresses the disclosed upgrade.
Is my modded Game Boy Advance SP insured when I take it outside?
Home cover does not establish away-from-home cover for your modded Game Boy Advance SP. Check the portable contents or personal effects terms, including the covered events and geographical boundaries.
Will insurance replace my console with the same themed edition?
An identical themed replacement is not guaranteed unless the applicable settlement terms establish that outcome. Ask how the insurer handles the documented shell, display and charging modifications.
Does a console warranty cover a cracked screen after a drop?
A warranty does not establish cover for a cracked screen caused by a drop. Read the warranty terms and check accidental-damage insurance separately.
Should I get my damaged Game Boy Advance SP repaired before claiming?
Contact the insurer before authorising repairs and follow its claims instructions. Ask what evidence, assessment and approval it requires, and retain the damaged console and parts.
One last thing
Ask what the insurer would replace your console with—not just whether it is covered. Acceptance of a claim and satisfaction with the replacement are different questions.
Before your next 2026 renewal, put the display, charging conversion and exterior description beside the settlement wording. Resolve any mismatch while the handheld is intact; that is the clearest way to avoid relying on protection that does not match your rebuild.